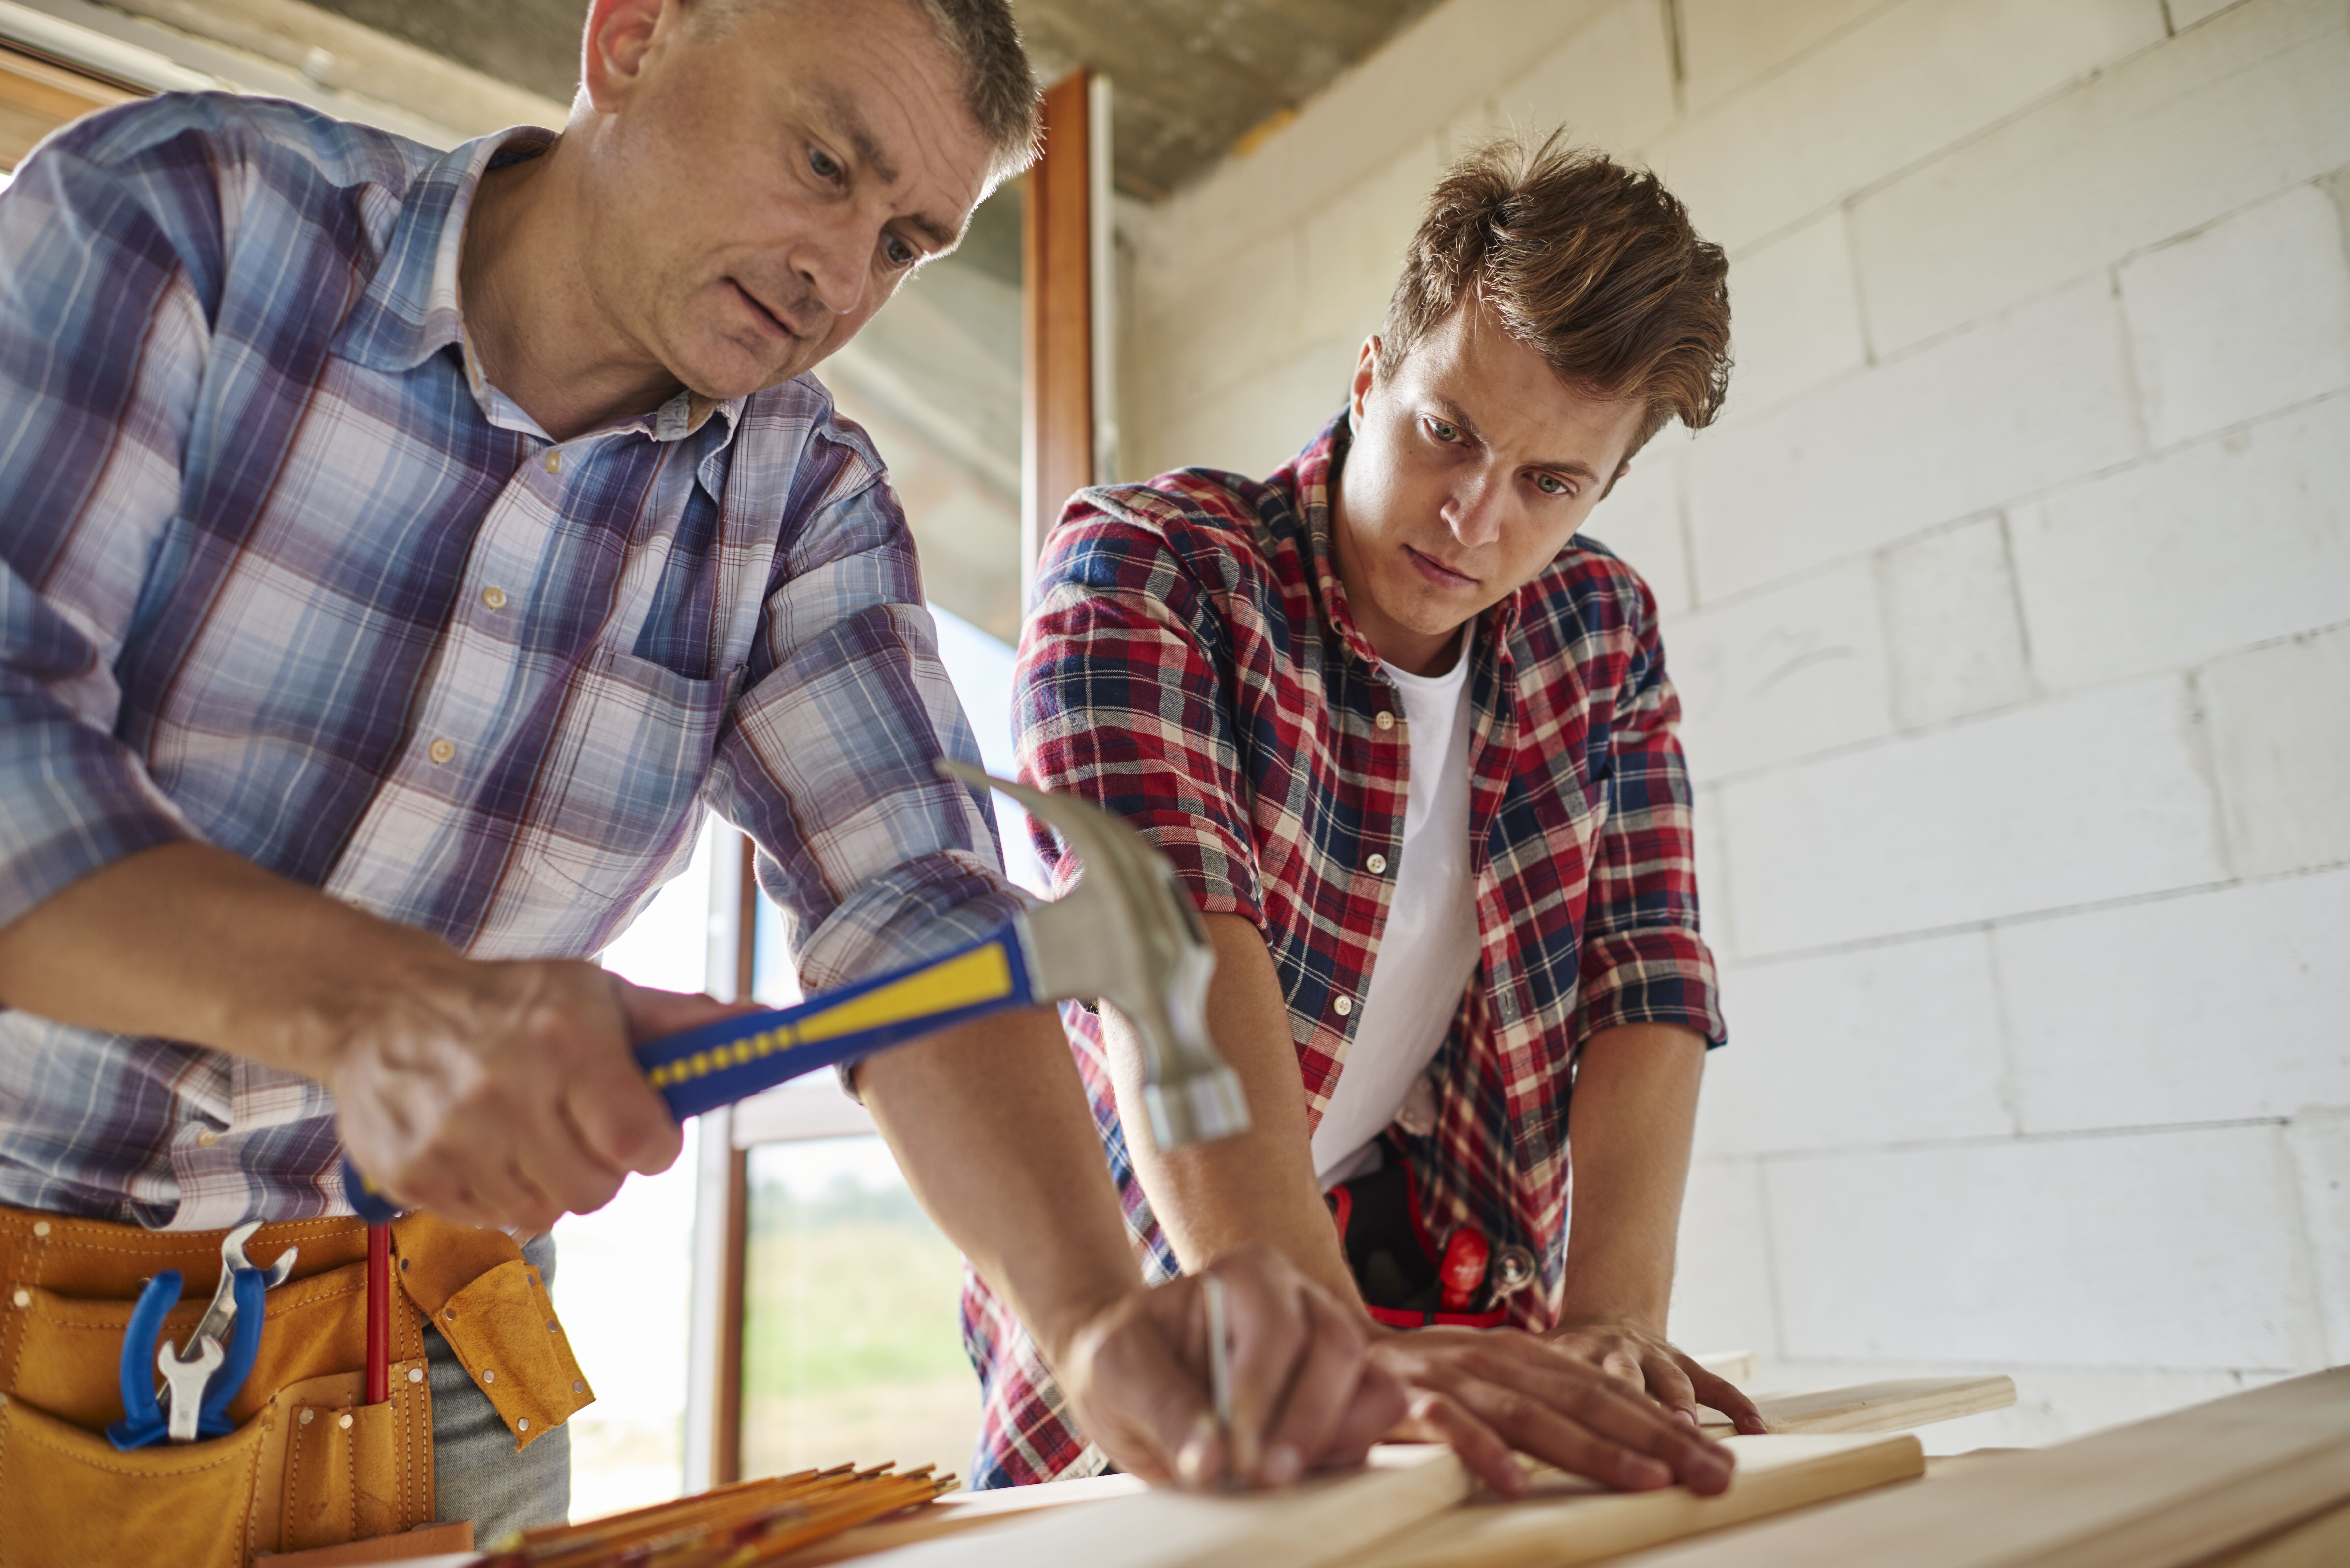

Woodworkers face several legal and liability risks when working in customers’ homes. From damage to property to injuries and disputes over work quality, these risks can hurt your business if not handled properly. Knowing what problems might come up helps you protect yourself and your woodworking business.
Carpenter Saver has provided insurance for woodworkers and carpenters since 1984. We’ve helped thousands of professionals get the right protection for their work. Our policies cover everything from public liability to professional indemnity. We make insurance simple and affordable so you can focus on creating great woodwork.
Risk #1: Property Damage
Working in someone’s home means you might accidentally damage their property. Even careful woodworkers have accidents. You might drop a tool and crack a tile, let sawdust get into electronics, or install a shelf that later falls and breaks items below it.
The costs of fixing property damage can add up quickly. UK law says tradespeople must pay for damage they cause while working. These costs could be small or large enough to put your business at risk. Having good public liability insurance for woodworking protects you from paying these costs yourself.
Risk #2: Personal Injury Claims
The second major risk is personal injury claims. If a customer, their family member, visitor, or another worker gets hurt because of your work, you could be responsible for paying them.
Common injury situations include:
- Someone getting hurt by tools or materials left out.
- People tripping over equipment or wood scraps.
- Health problems from breathing too much dust.
- Injuries from half-finished projects.
UK law expects tradespeople to keep their workplace safe, even in someone else’s home. Claims can include medical bills, pain compensation, and lost wages – sometimes costing thousands of pounds. Public liability insurance designed for woodworkers helps cover these costs.
Risk #3: Projects Don’t Meet Expectations
The third big risk comes when customers aren’t happy with your work. They might refuse to pay, ask for major changes, or even take legal action if they believe your work caused them financial loss.
These problems often start with misunderstandings about what the project should include, how long it will take, or what the final result should look like. Without clear written agreements, it’s your word against theirs. Beyond legal costs, your reputation might suffer, causing you to lose future work. Professional indemnity insurance helps protect you in these cases by covering legal costs and possible compensation.
Risk #4: Health and Safety Compliance Issues
The fourth risk involves following workplace health and safety rules. These rules apply even when you’re working in private homes. You must:
- Check for risks before starting work
- Handle and store materials and tools safely
- Control and remove sawdust properly
- Use the right safety equipment
- Dispose of waste correctly
Not following these rules can lead to heavy fines. Worse still, if someone gets hurt because you didn’t follow the rules, you could face criminal charges on top of civil claims. Regular training and good safety habits help reduce these risks, but having proper liability insurance is still essential.
Risk #5: Liability for Your Work Long After Completion
Many woodworkers don’t realise they can be held responsible for their work years after the job is done. Under UK contract law, customers usually have six years (five in Scotland) to make a claim for poor workmanship. The limit for negligence is also six years. However, if the issue only comes to light later, customers may have up to three years from when they discover it, capped at 15 years from the date the work was finished.
This long-term risk matters most for structural woodwork, like staircases, built-in furniture, or load-bearing shelves. If something fails and causes damage or injury, you could face legal claims long after you’ve moved on to other projects.
That’s why the right insurance is essential. Products liability insurance can cover injuries or property damage caused by your work or materials. But for claims about poor workmanship or advice, you may also need professional indemnity insurance. Always check your policy to make sure it matches your business needs.
Protecting Your Woodworking Business
Running a woodworking business means more than just delivering quality craftsmanship. It also means protecting yourself from unexpected risks. The right insurance and solid documentation practices can safeguard your livelihood and reputation.
Essential Insurance Coverage
To fully protect your woodworking business, you need several types of insurance:
- Public liability insurance (at least £1 million, but £2-5 million for bigger projects)
- Products liability protection for completed work
- Professional indemnity coverage for work quality disputes
- Tools and equipment insurance
- Employers’ liability insurance if you have workers or apprentices
Documentation Best Practices
Good paperwork reduces your risks. Always:
- Use detailed written contracts that clearly state the work, materials, timeline and payment terms
- Take photos before, during, and after projects
- Keep receipts for materials and quality certificates
- Write down all customer communications, especially about changes
- Give customers written care instructions for your woodwork
Keeping good records helps prevent disputes and provides important evidence if claims happen. When you combine good documentation with proper liability insurance from specialists like Carpenter Saver, you create a safety net that lets you focus on your craft instead of worrying about potential problems.
Partner with Carpenter Saver
Understanding these five key liability risks and taking steps to manage them will help protect your woodworking business while you create beautiful custom pieces in customers’ homes. Get a quote to start protecting your woodworking business today.